

 Market
The “Land Grab” Is Over: Welcome to the Performance Era of Brazilian iGaming
André Moreira
The “Land Grab” Is Over: Welcome to the Performance Era of Brazilian iGaming
Brazil’s betting market has entered a new phase — and the companies that recognize this shift early will likely gain a significant strategic advantage over the coming years.
For a long time, the Brazilian iGaming industry was defined almost entirely by expansion. The market rewarded speed: rapid customer acquisition, aggressive marketing, massive sponsorship activity, and the constant arrival of new operators competing for scale.
In 2026, that dynamic is beginning to change
What was once primarily a market-entry race is evolving into a highly competitive environment driven by operational performance, efficiency, retention, and execution quality.
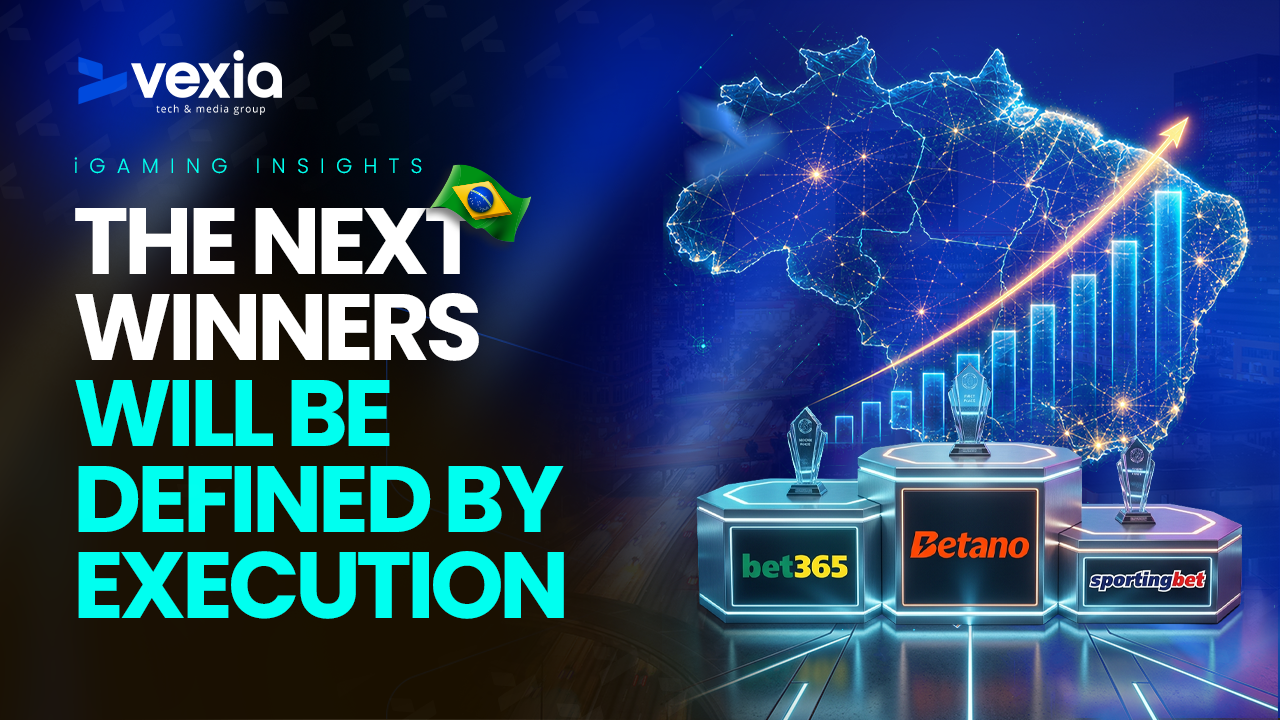
Recent data from Blask reinforces this transition. Betano consolidated its leadership position with an estimated US$1.09B in Combined Estimated Bets (CEB), while bet365 and Sportingbet continue to demonstrate strong market resilience. At the same time, challenger operators such as Superbet are scaling aggressively, posting year-over-year growth above 90%.
The most important signal isn't necessarily who currently leads the rankings.
The real shift is that Brazil is no longer behaving like an emerging opportunity market. It is increasingly behaving like a mature competitive ecosystem, where acquisition costs rise quickly, differentiation becomes more difficult, and operational quality starts to matter more than expansion alone.
The scale of the regulated market helps explain why this transition is happening so fast.Source: Blask, iGaming News Today and Brazilian regulated market data (SPA/MF).
Official market data already indicates more than R$36.9 billion in GGR during the first regulatory cycle, alongside over 25 million unique bettors and a rapidly evolving compliance and enforcement structure.
As regulation advances, operators are being forced to adapt to a more demanding environment — one defined by higher fiscal pressure, stricter monitoring standards, mandatory verification processes, and growing expectations around responsible gaming.
This fundamentally changes the competitive equation. Early-stage markets typically reward presence.Mature markets reward execution. And execution, in the current Brazilian environment, is becoming increasingly multidimensional.
Retention strategies are now as important as acquisition performance. Operators can no longer rely exclusively on aggressive traffic buying to sustain growth. CRM sophistication, loyalty ecosystems, localized content, and long-term player engagement are becoming critical competitive differentiators.
Operational efficiency is also becoming more important. As taxation, compliance costs, media competition, and sponsorship spending continue to rise, maintaining healthy margins will depend on leaner and more scalable operational structures.
At the same time, product experience is becoming a decisive factor. Brazilian users are increasingly sophisticated and less tolerant of slow platforms, poor UX, generic offerings, or inefficient payment experiences.
Perhaps most importantly, compliance itself is evolving into a strategic capability rather than a regulatory obligation. Companies with stronger governance, faster adaptation to regulatory requirements, and more mature operational controls are likely to gain structural advantages as the market professionalizes further.
The most relevant question in Brazil today is no longer who entered the market first.
The real question is who will continue growing once the market becomes significantly more competitive, more regulated, and considerably more expensive to operate in.
Brazil remains one of the largest opportunities in global iGaming.
But it is no longer simply a growth story.
It's becoming one of the most competitive and professionally structured betting markets in the world.
Share Article